
FIN 3515
Corporate Financial Management
Prof. Tony Okoromadu
By the end of this course, if we work together, I am confident you will be capable of examining the financial statements of any corporation anywhere in the world (ie. regardless of the presentation format conventional in its geographical jurisdiction) and confidently narrate the story of the corporation's performance, doing so - and this is important - in a manner that a non-finance practitioner can comfortably understand, yet without compromising depth or profundity of subject.
Course Description
The college catalog specifies that the principal goals of this course “are to provide the concepts and techniques required to make long-term investment and financing decisions within the firm”. It further states how, “At the end of the course, students will be able to make real asset investment decisions by valuing a proposed investment project or acquisition”.
We shall be pursuing this with a hands-on approach, learning the core theories, concepts and mathematical tools to corporate finance, carrying this out in a manner that is case-study and project-based. And so, while corporate finance can seem intimidating, we will make it less so by applying its concepts, formulas and practices to current real-life scenarios. Our approach will focus on contemporary (and in some instances, real-time) events and developments in the lives of corporations from different parts of the world and across various industry sectors.
"Shall I, Shall I Not?"
Why This Course Might Be For You
As an undergraduate business school student, you will be required to take a specified minimum number of finance course credits - but you are not required to like finance. Indeed, you do not need to feel an affinity for finance in order to become a high-achieving professional in a business-related field. Nonetheless, a proficient knowledge of how corporations set about managing their totality of assets (financial and non-financial) and efficiently harness all of these towards generating economic value and competitive performance in their industry sector, is a competency that could not let you down but could only bolster your value proposition in the career market. And the welcome news is that this proficiency is entirely attainable by you: the fact that you are capable of studying for an undergrad degree in a prestigious business school strongly suggests that you are capable of grasping - to a high level - the essentials to a corporation’s management of its finance affairs.
If you do have an affinity for finance and already are intent on it as an undergraduate specialty, a proficiency at corporate finance could afford you a crucial view of the business corporation and its operations as a holistic entity, distinct from studies of different component aspects to the corporation’s financial structure, which other finance subjects such as investments, portfolio management, etc would offer.
- “I am not sure that I love finance but I would like to become an entrepreneur, a CEO, or a part of the leadership team of a corporation one day.”
Here’s an interesting observation: statistically ( allowing for different industry and geographical regions, etc.) you frequently will find that only a minority of CEOs of leading corporations have an undergraduate major in finance. A larger proportion are likely, for example, to have majored in accounting, economics or engineering, particularly. More than their specific undergraduate preparation, what these CEOs tend to have in common are a broad operational leadership experience with its attendant skillsets, which - invariably - are developed over several years across a career path that takes in various cross-functional roles.
......
As an interesting exercise, you might press your preferred AI model into service and explore what the ramifications of a finance undergraduate degree might be for a CEO (or company director) role. One of the major AI models, when asked to design the ideal executive from scratch, based on relevant research data, came up with this set of qualities:
- Financial depth: Enough to understand capital allocation better than almost everyone around the table.
- Operating depth: Enough to know what happens when strategy meets reality.
- Commercial depth: Enough to understand customers and revenue.
- Strategic depth: Enough to see where the industry is going.
- Human depth: Enough to attract, develop and retain exceptional people.
- Governance depth: Enough to work effectively with a board.
“Such a person doesn't really belong to a function anymore. That's a CEO.,” it concluded.
(This is, of course, a simplified version of what would actually be a more nuanced enquiry and care should be exercised in framing its parameters and central question, as well as in interpreting the results. Nonetheless, some observations might be safely stated.)
......
A good grasp of matters corporation finance would be a valued competency for a company director or member of executive management.
- “I am quite interested in finance and have taken - or intend to take - various specialized finance courses such as those dealing with securities, valuation, portfolios management, etc. Why should I take this one?”
You probably are looking to a career in asset management, investment banking, private equity and the like. You may think of these as specialties within the finance industry sector, akin to how pediatrics, neurosurgery, endocrinology, etc. are individual specialties within the field of medicine. A hospital managing director (CEO) is most often not a medical doctor; and when they are, they won't necessarily be the most accomplished specialist in their specific medical area. The skill set required for the role of effectively managing and running a hospital establishment is different than the one required to perform successful brain surgery, say. And while both those roles might be found in a large hospital, competence at one of them does not by itself translate to competence at the other - and it need not.
Analogously, specialties within finance are just that; and a career could be built in one specialty from start to finish, similar to how a cardiologist could do the same. Understanding how the entire corporation (or hospital) with all its resources (human, physical and financial assets) functions as one holistic yet compact unit, would be necessary if one wished to direct or manage the entire organization. Such a function would differ (and require a separate set of skills, knowledge and experience) from what would be needed for a specialist role that - in effect - is a support function for the organization. (As a consequence, for example, an MBA degree has historically often been seen as the crossover academic qualification that prepares a specialist function - or other entirely different professional discipline - for the more holistic skill and knowledge set that the management of an organization requires.)
For a CFO role, competency at corporation finance management would naturally be an indispensable requirement.
Course Methodology
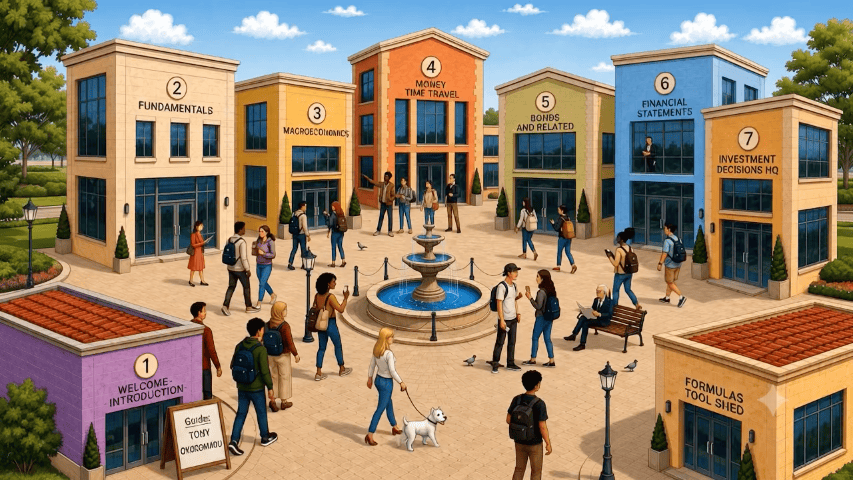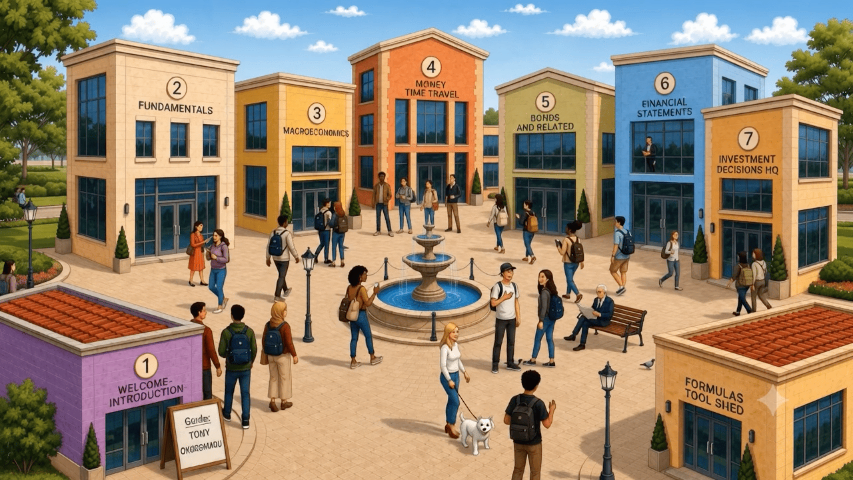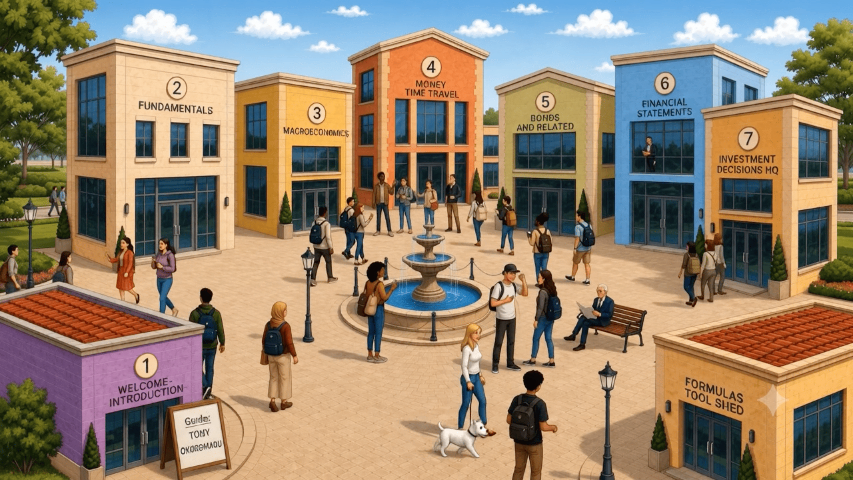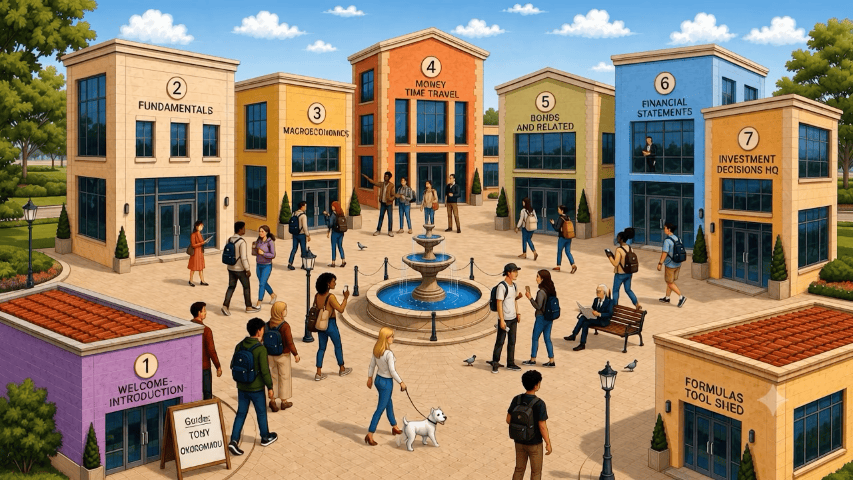
We are embarking on a metaphorical tour of Main Street, where we will encounter and spend time in each of its buildings. Each building is dedicated to a specific field of work connected to corporate financial management and we will learn about these fields in depth so that by the time we move on to the next building we would have acquired the knowledge and developed the skills and competencies that the field requires - a sort of learning apprenticeship.

Each building will comprise a chapter of our course, we will largely be visiting the buildings sequentially; however, we will quite often find ourselves revisiting a building (when we need to quickly brush up on some of its dedicated knowledge or skills).
Our approach to learning corporate financial management will be conceptual. The student should be able to make a connection between the subject matter and how it relates to contemporary real-world procedures, tasks and outcomes, we will avoid a rote memorization of formulas and processes. And so we will adopt a posture of adequately understanding the subject topics from their conceptual bases and then, on that foundation, build up to the subject’s specific intricacies of quantitative and intellectual rigor and complexity. We will build around the What, Where, How, When, regarding the concepts in corporate financial management. For every topic, we will explore what the concept and its real-life application mean. In other words: what is the concept, where is it used, how is it used, when is it used.
It is not accidental that the last building on our street tour has no number on it, meaning we do not consider it to constitute a fundamental chapter to the key competencies required in finance. It is the building where all the finance formulas are housed: formulas are a tool, they are indispensable just as screwdrivers and socket wrenches are indispensable to a automobile engineer, but the engineer's expertise is not built around their dexterity at their tools; instead, the competent engineer has confident knowledge of how the car engine works, can troubleshoot the engine's problems and then on that basis determine which tools will be required for the task. Expert knowledge of tools is not the key. Similar in finance. And so, we will be placing formulas in a tool shed and - like the engineer - will reach for the appropriate formulas when they are needed.
Course Structure
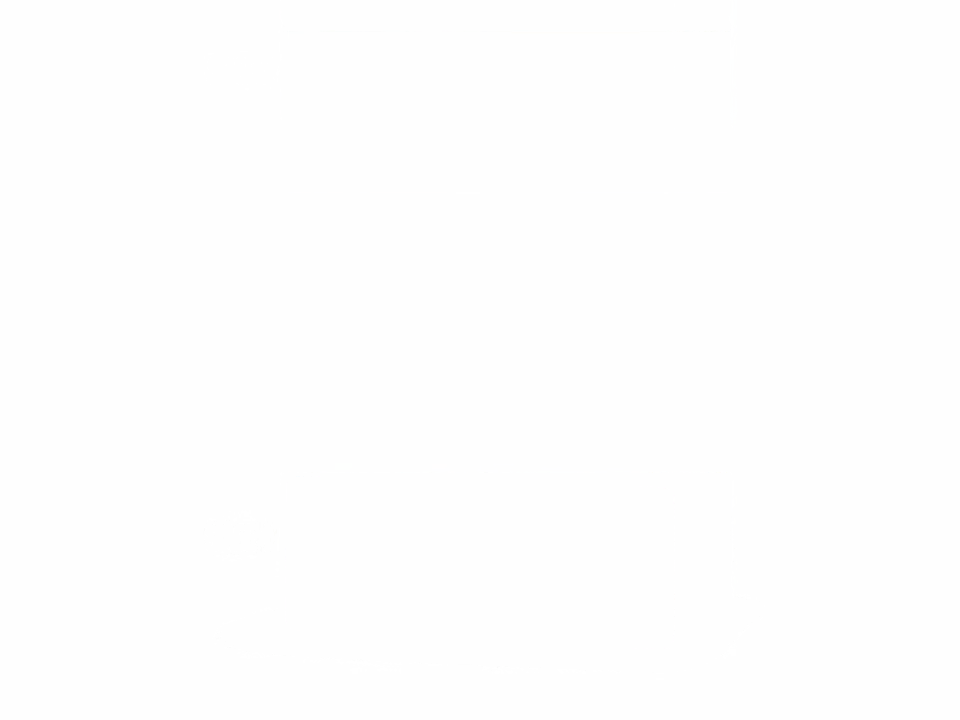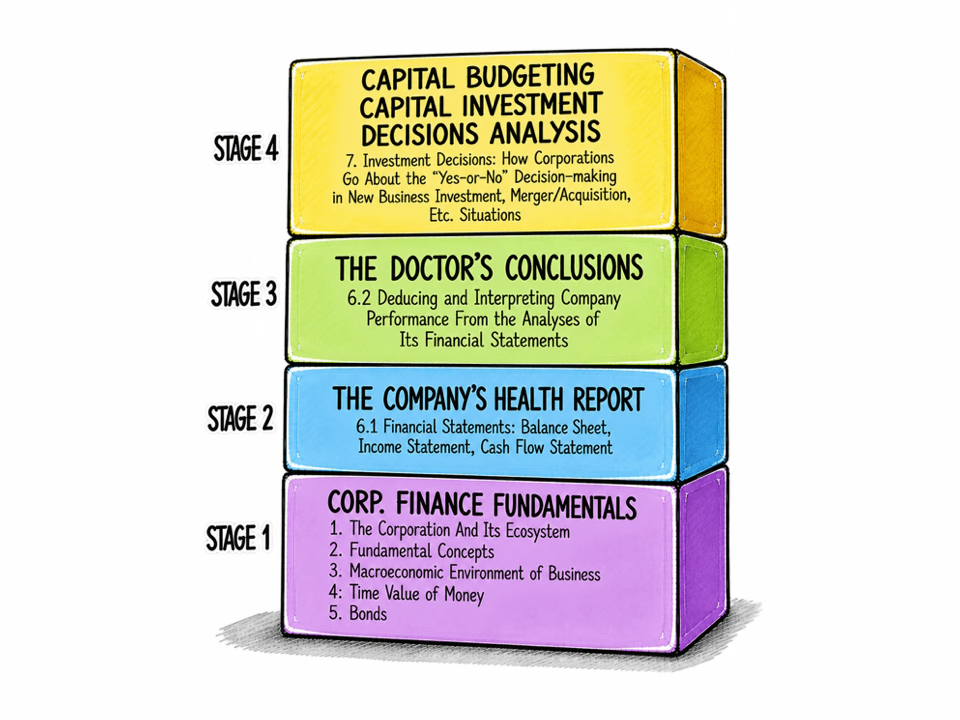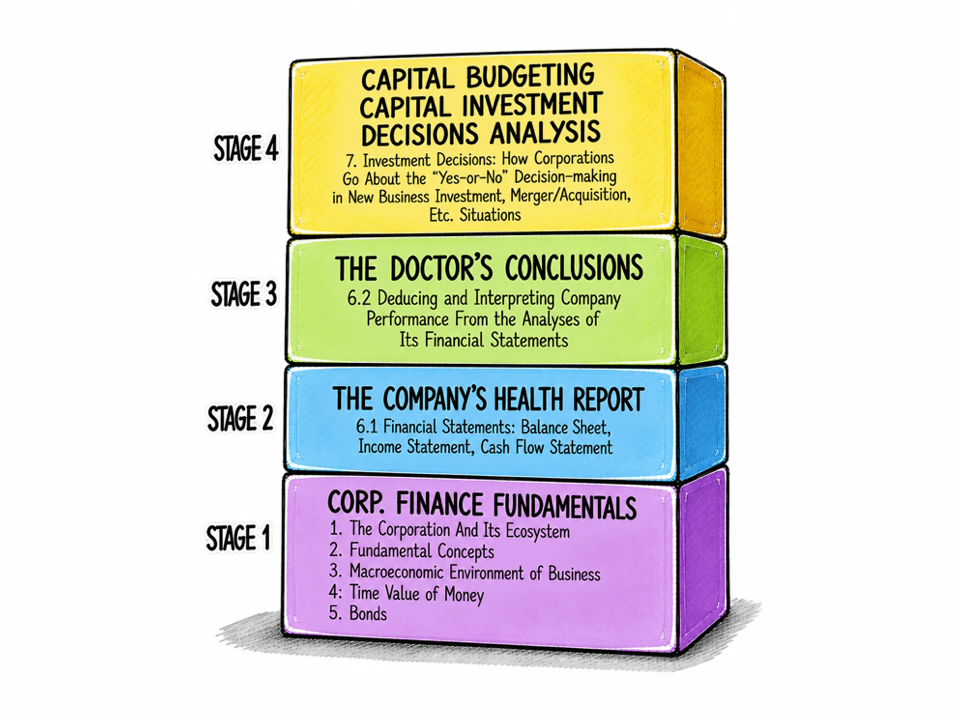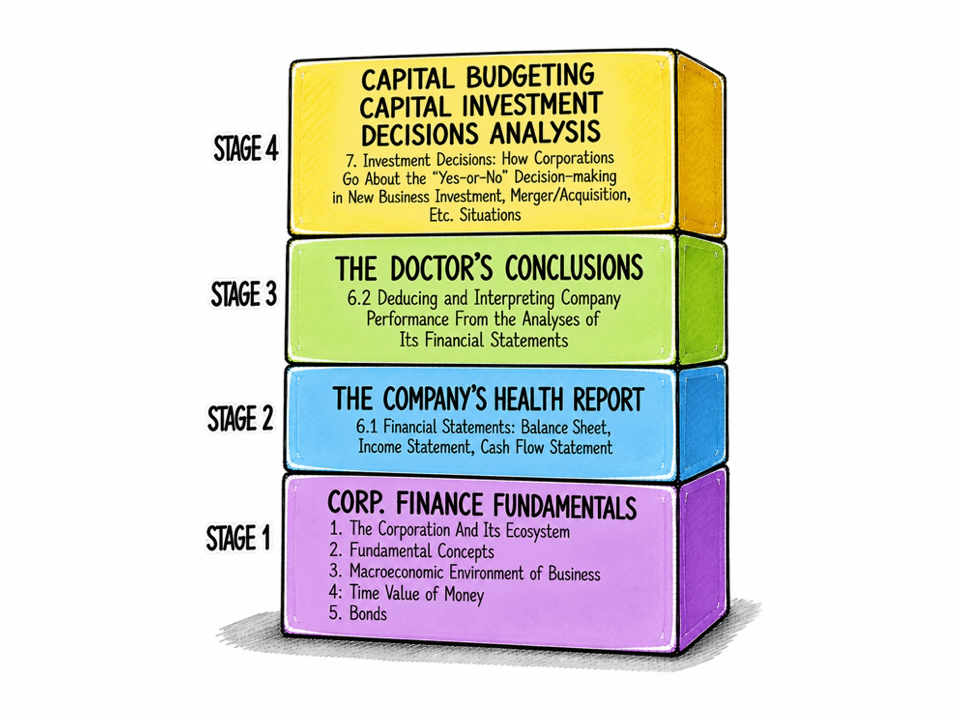
There are four stages to our course journey, each stage comprised of the respective buildings of our Main Street. (A detailed breakdown of the chapters is at the bottom of this webpage.)
......
Stage I: Corporate Finance Fundamentals
1. The Corporation and Its Ecosystem
2. Fundamental Concepts
3. Macroeconomics and the Corporation
4. Time Value of Money
5. Bonds
Stage II: The Company's Health Report
6.1 Financial Statements: Balance Sheet, Income Statement, Cash Flow Statement
Stage III: The Doctor's Conclusions
6.2 Deducing and Interpreting Company Performance From the Analyses of Its Financial Statements
Stage IV: Capital Budgeting | Capital Investment | Decisions Analysis
7. Investment Decisions: How Corporations Go About the "Yes-or-No" Decision-making in New Business Investment, Merger/Acquisition, Etc. Situations
......
(I like to teach chapters 6 and 7 using opera references, as though the finance concepts were members of the cast in a theater production. Thus you will encounter Madame Balance Sheet and Monsieur Income Statement in chapter 6, alongside Mademoiselle Cash Flow Statement; each of them, when we visit backstage, will explain their role and its purpose and place in a corporation's operations - the theater performance itself. They will also explain how they tend to work as a team. In chapter 7, there will be Ms. IRR and Mr. NPV, who will do the same. I find that this approach helps the student understand and relate to the concepts effectively.)
On the journey, in addition to the strictly finance topics, we will make brief detours and work on some adjacent skills and competencies. For example:
Data Visualization Session
- because the ability to effectively and aesthetically convey otherwise complicated information by means of charts might seem a bland skill set; au contraire, it is actually rare and much prized.
Group Presentation
- because being able to efficiently and persuasively deliver your ideas to an audience is a skill that will always give you a competitive edge in your career, and it requires practice.
Career Networking Session
- because networking is indispensable and you want to be adept at it in a manner that is natural and builds a confidence about you in the people you will encounter.
Sprinkled along our tour, and popping up at various points:
Ethics
- because guided by its principles your career and life will convey an authentic self-assurance and conviction that build you a store of resilience.
Real life, real-time corporation case studies
- we will learn by applying corporate finance principles and procedures to real life companies and their latest published business and financial information; frequently, you will yourselves select the focus corporation during our class session.
Your Weekend Read
- carefully curated articles plucked from contemporaneous business media news stories that have a bearing on our class topic(s). You will benefit by seeing class theory played out in real life, in real time.
Your AI is welcome
- we will deploy AI (particularly LLMs) in class as we explore corporations and their financial management practices.
Course Assessment
(further specified in the course syllabus document)
-
Participation
-
Various assignments and tasks
-
Group Project
You with your colleagues will constitute a firm of consultants looking into a set of competing corporations in an industry sector of your choosing; you will comparatively assess their business/financial management outcomes over a particular period of years within a particular set of constraints. Real companies, real-life constraints, real-life financial statements and declarations.
-
Individual Project
You will be a consultant hired by a corporation and tasked with assessing the viability of a multimillion dollar (or euro or british pound sterling) multiyear capital investment project. A real life simulation including in its macroeconomic and geopolitical dimensions.
Student Outcomes
(greater detail in the course syllabus document)
By the time we’re done with our semester, you should be able to sit around a management (or board) table and confidently understand corporation finance deliberations, asking the right questions, drawing the correct inferences, even if your specialty is as far off from finance as, say, advertising. (Or even if it is as far off as The evolution of structured prose in 14th century renaissance literature, bless.)
Plus - quite importantly amongst other outcomes - you would be adept at talking corporate finance in plain enough language, without resorting to stifling your interlocutor with a rapid avalanche of finance terminology, expecting that they surrender to this “inscrutable, complex” field (it isn’t) that is accessible only to the seasoned “experts” (untrue).
You will also come away with two professional class documents that could form impressive parts of your personal portfolio and showcase your corporate finance capabilities to employers and recruiters.
Corporate Financial Management
A Structured Walk Down Main Street
Course Content
(Summarized version. Complete version will be available on Canvas.)
The general outline of our course, with its chapters and topics. Corporate Financial Management is a wide field with intense topics and we shall aim to cover them as listed here. As stated in our syllabus, some tweaks may be made to them as we journey through the semester, if the adjustments portend more effective understanding. For example, breaking news events relevant to our subject matter might occur, in which instance we shall try to inject them into the curriculum where possible.
The contents here might appear intimidating, but there is no need to worry about that at all. I assure you that, if we work diligently together, you will be able to grasp the core of these various finance concepts’, their meaning, purpose and methods. At the end of our semester together, I am confident that you will look back and be earnestly proud of what you achieved.
Stage I
1.1 Introduction
General overview of the purpose of an education • Critical thinking & analytical reasoning • Societal impact of every individual • Global mindset • Noble ambition • Big picture • Class methodology • Babson College Learning Competencies and Educational Themes • Etc.
Course overview.
1.2 The Corporation and its Ecosystem
What you will learn
What/who is a company. What and who are stakeholders. Who wants what, owes what, needs what. What are the rights and obligations involved. Corporate social responsibility. Ethics. How a business is typically set up.
The typical structure of a company: at inception, growth, etc • Forms of business organization • How relevant is an ethical dimension to business? • What - quite frankly - is in it for me? (This is an important question and it demands a cogent response founded on pragmatic real life and not floral niceties.) • How might a corporation's ethics framework affect its performance and competitiveness? Personal ethics • Company ethical and legal responsibilities • Defining and prioritizing stakeholders • What are the rights and obligations involved: who wants what, owes what, needs what? • Corporate Social Responsibility • Entrepreneurship and start-up (ethics) culture • Goodwill and the balance sheet • Etc.
2. Some Fundamental Concepts: A Welcome Guide
What you will learn
Finance terms often deceptively sound more complicated than they actually are. They can actually be not that difficult to grasp. For example, a Derivative is simply anything that can be traded (bought and sold) but which in itself holds no material value, instead deriving its value (ie. the amount of money it commands at trading) from something else (its underlying asset). For illustration, consider that an Options is a contract (for the purpose, simply picture it as a signed paper document) to purchase some item in the future. In itself, the signed document is merely a piece of paper. However, that piece of paper might be in reference to 100 barrels of crude oil, sitting in a refinery. Whoever holds the piece of paper has claim to the 100 barrels of oil. When that piece of paper is able to change hands (some other party buys it from its current holder), it becomes the financial instrument known as a Derivative, and it would be worth a sum of money that reflects the monetary value of the 100 barrels of oil it represents; those barrels of oil become the piece of paper’s underlying asset.
Continuing that line of thought, the Options contract will have a changing market value over time, because its value at trading will reflect what people estimate the 100 barrels of oil will be worth when the time comes for the holder to retrieve them. If there is forecast of a natural disaster, for example, around the period when the 100 barrels of oil are to be collected, and people expect crude oil to therefore become scarce, the trading value of that same Options contract will go up (to reflect the expectation that oil prices at that future period will be higher than they might be at the present moment), because whoever holds the Options contract is guaranteed the 100 barrels of oil, no matter the level of scarcity at that future period. A Security (plural, Securities) is a financial instrument, and a financial instrument in turn is anything that can be traded in an organized market set up for the purpose. And so, an Options is a form of Security, just like Stocks, Bonds, etc, are also.
This is a simplified explanation, but it adequately captures the essence of these terms and is enough for you to comfortably understand their meaning and use in finance. You will be comforted to know that this “more-straightforward-than-one-might-have-assumed” characteristic is common to many concepts, terms and practices employed in corporate finance and finance in general.
(Not in any particular order. Not exhaustive.)
Equity • Debt • Investment funds • Mutual funds • Hedge funds • Sovereign wealth funds • Risk-Return trade-off • Stand-alone risk • Risk in a portfolio context • Expected portfolio returns • Cash flow • Time value of money • Balance Sheet • Income Statement • Statement of Cash Flows • Statement of Stockholders’ Equity • Limitations of financial statements • The Annual Report • The stock market • Stock market indices • Working capital • LBO • Derivatives • Options • Futures • Indexed Funds • Passive and Active Investing • ETF • Venture Capital • Financial Markets • Private Credit • Etc.
3. Macroeconomics and the Corporation: A Quick Visit
What you will learn
The external financial and economic milieu within which a corporation operates. Much of this external environment is beyond the corporation's control and as such it must manage its many elements as nimbly and pro-actively as possible, always looking to do so in a manner that is consistently superior to, and more efficient than, its rivals’. We will only deal with the minimum necessary here, macroeconomic environment of business is an entire field of study on its own.
Gross Domestic Product • Gross National Income; Real and Nominal Indices • Inflation • Interest Rates • Exchange Rates and Currency Valuation • Consumers Interaction with the Economy.
Transborder Transactions, Imports, Exports • Foreign Direct Investment (FDI) and Cross-Border Mergers & Acquisitions •
International Money Market • International Bond Market • International Equity Markets • Interest Rate Parity • Foreign Exchange Exposure and Management • Management of Economic Exposure • Multinational Cash Management
4. Time Value of Money: Money Time-Travel
What you will learn
How money time-travels, and the changing real worth (purchasing power) of the original amount of money at various points in that travel, down the years. The prospective (future) real worth of the money helps determine whether the travel is worth its while. The effort put into the journey might not be worth the while if, at its arrival at destination, the money ends up being worth less (purchasing power) than it was at the journey’s start. (The value of the money at end-of-journey could be less than it was at the beginning-of-journey, even if the nominal money “volume” itself is greater at the end-of-journey. $1,200 might be worth less ten years from now than $1,000 is worth today, because $1,200 might buy you fewer goods in the year 2035 than $1,000 would buy you in the year 2025.) In this chapter you will learn how this factors into a company’s financial projections and how it is an important criterion for decision-making with respect to what projects a company decides to undertake.
Time lines • Cash flow • Future values • Present values • Hurdle rates • Annuities • Perpetuities • Uneven cash flows • Compounding periods • Operating cash flow • Free cash flow (FCF), aka Free cash flow to the firm (FCFF)
5. Bonds
What you will learn
The origin and nature of bonds and the mechanics and logic of bond valuation. You will see how bonds and the interpretation of their price and earnings movements etc. are not complicated to understand.
Key characteristics of bonds • Par value • Coupon interest rate • Maturity date • Call provisions • Bond yields • Bond risks • Bond markets
Stage II
6.1 Balance Sheet, Income Statement, Cash Flow Statement: The Corporation's Medical
What you will learn
How company financial statements are analogous to a person’s “yearly physical”: their medical laboratory (and other standard) test results. A health professional would examine those results and be able to draw inferences about the person’s health status and then draw up a medical report.
Stage III
6.2 Financial Statements Analysis: The Doctor's Conclusions
What you will learn
While interpretations and advised remedies may reasonably differ sometimes from one doctor to another (hence desire for “second opinions” - so-called even when more than two - in those instances), similar conclusions will still be drawn among different doctors. The same applies to a company’s medical test results: its financial reports. You will learn how to interpret them here, in chapter 6. By the end of the chapter, you should be able to glean deeper inferences and implications from a company’s financial statements, knowing what probing questions to ask of the company and what financial ratios (conventional or improvised) need be applied in the process.
Ratio analysis • Operating efficiency ratios • Liquidity ratios • Asset management ratios • Debt management ratios • Profitability ratios • Market value ratios • Using ratios to assess company performance
Stage IV
7. Capital Budgeting, Capital Investment, Decisions Analysis
What you will learn
The considerations that inform how and where a company goes for its funding, and how it goes about determining the proportion of said funding it should get from the different sources when, as is often the case, it has more than one funding source. That eventual funding composition (its funding mix) will have a cost (the fees the company incurs for the funds, eg. interest rates it must pay on loans) and the total cost of its funds portfolio will be the aggregate cost of the funds taken together. (The total cost of each funds group in proportion to their percentage make-up within the total funds, ie. the size of the funds group relative to that of the overall portfolio. Analogous to how your cumulative GPA is the aggregate sum of your GPA scores on each of your courses in proportion to the number of credit units the course represents.) This aggregate cost of capital is called the WACC, Weighted Average Cost of Capital. WACC is an important factor in determining whether a company’s funding mix is efficient and not end up negatively impacting the company’s profit levels in the end, because the aggregate cost is not much lower than the expected earnings (for the moment consider this as the profit, loosely speaking) from the project/investment.
Cost of debt • Aggregate ie. “Weighted” average cost of capital (WACC) • Capital budgeting • Revenue and expenditure forecasts • Investment decision-making • Net Present Value (NPV) criterion • Investment Rate of Return (IRR) criterion • NPV profiles • Payback period
● ● ●